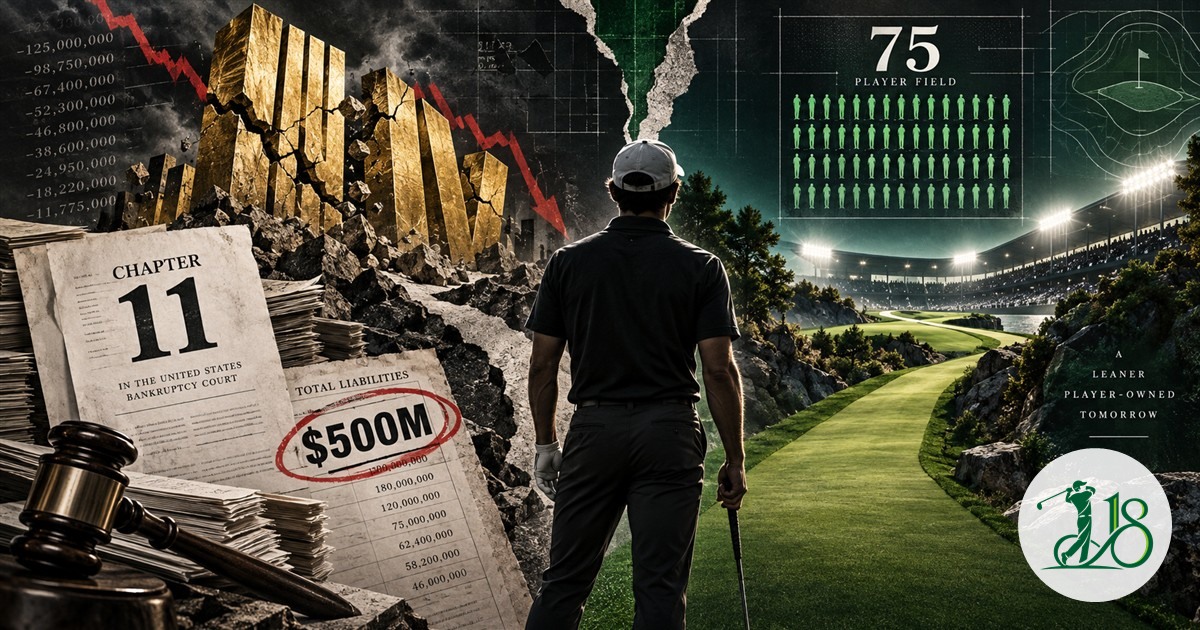
Quick answer: LIV Golf filed for Chapter 11 bankruptcy protection Tuesday in New Jersey with more than $500 million in debt. The league says a restructuring agreement with BC Partners Credit is intended to preserve the business, install a player-majority ownership model and allow an early-2027 emergence. Saudi Arabia's Public Investment Fund has agreed to provide $49.6 million in debtor-in-possession financing, subject to court approval.
The possibility that hung over LIV Golf for weeks became a court filing Tuesday. LIV Golf Incorporated and affiliated entities voluntarily entered Chapter 11 in the U.S. Bankruptcy Court for the District of New Jersey, moving the breakaway league from financial uncertainty into a formal restructuring process.
The filing does not mean LIV disappears immediately. Chapter 11 is designed to let an organization continue operating while it restructures obligations under court supervision. But it does replace promises about a future league with enforceable deadlines, creditor claims and judicial approval. For players, vendors and fans, that is the most consequential LIV development since Saudi Arabia's Public Investment Fund decided to end its open-ended financial support.
Associated Press reported more than $500 million in debt. LIV's own announcement says the company has a restructuring support agreement with BC Partners Credit and intends to emerge in early 2027. The proposed business would be majority owned by players still negotiating their participation, with BC Partners and potential minority investors supplying exit financing.
What Chapter 11 changes today
LIV remains a business in operation, but it no longer controls the next phase alone. Major transactions, financing arrangements and the treatment of creditors move through a court-governed process. The league must persuade the court and affected stakeholders that its restructuring plan is feasible and fair under bankruptcy law.
The immediate financial bridge is $49.6 million in debtor-in-possession financing from PIF. That money is not a return to the old funding model. It is interim financing intended to support the company during the case, and it remains subject to court approval. DIP lenders typically receive priority protections, making the arrangement a controlled bridge rather than a blank check.
LIV also said it is seeking recognition of the U.S. proceeding in England and Wales to protect international assets and operations. That detail matters for a league whose events, commercial relationships and workforce span several countries. A restructuring centered in New Jersey still needs mechanisms that make its orders meaningful across borders.
In April, CEO Scott O'Neil publicly insisted that the 2026 season would continue despite funding concerns. The official Sky Sports interview above captures the position before the league's finances moved into court supervision.
The proposed future is smaller and player-owned
LIV's pitch is not simply that bankruptcy will erase debt. The company is asking stakeholders to support a different league. Its announced framework centers on players holding a majority ownership interest, an idea intended to align stars with the value and risk of the enterprise rather than treating them only as guaranteed-contract employees.
The league has also outlined a reduced schedule and a larger playing field. LIV competed with 57 players in 2026; the proposed next model calls for 75 and introduces a 54-hole cut. Those changes point toward a product that borrows more from traditional tournament economics even while preserving LIV's team identity.
Player ownership sounds powerful, but the unanswered details are decisive. The value of any equity depends on the reorganized company's capital structure, media revenue, sponsorships, event costs and future funding. It also depends on which stars sign on. Bryson DeChambeau, Jon Rahm and other franchise-level names are not interchangeable with roster depth. Their decisions could determine whether the new league has a premium television product or merely a recognizable brand under new financing.
More than $500 million in debt changes the leverage
For years, LIV's competitive power came from capital. It could offer enormous guarantees, prize funds and team valuations without needing the near-term economics expected of an ordinary sports league. The bankruptcy filing reverses that leverage. Creditors, investors and the court now matter alongside players and league executives.
Four vendors had already sued over unpaid obligations, according to AP. Chapter 11 creates a centralized process for those claims, but it does not guarantee creditors will recover everything they are owed. The eventual plan will establish how different classes are treated and how much value survives after reorganization.
The debt figure also changes negotiations with players. A star deciding whether to accept equity must evaluate dilution, governance, cash compensation and the chance that the new company can operate sustainably. The original LIV proposition emphasized certainty: guaranteed money and a limited schedule. The reorganized proposition asks players to share ownership risk.
BC Partners is now central to the outcome
BC Partners Credit is the proposed plan sponsor and expected source of exit capital. Its role gives LIV a credible institutional counterparty, but the transaction is not complete merely because an agreement has been announced. Court and stakeholder approval remain required, and the final terms can change through the process.
The distinction matters. A restructuring support agreement shows that key parties have negotiated a pathway. It does not prove the league will emerge on schedule or that every player, creditor and commercial partner will accept the result. LIV itself acknowledged that significant work remains.
If the plan succeeds, BC Partners and other investors will inherit a company that still owns global event experience, team brands, media relationships and a roster of recognizable golfers. They will also inherit the task that unlimited Saudi funding postponed: proving that the product can generate enough recurring value to justify its costs.
What this means for the wider golf split
The filing arrives while LIV players are exploring other competitive routes. Some have entered DP World Tour qualifying, and Patrick Reed has positioned himself for a potential PGA Tour return. Geoff Ogilvy's unsuccessful request to consider LIV players for the International Presidents Cup team, reported earlier Tuesday, showed that existing eligibility barriers remain firmly in place.
Chapter 11 does not automatically release players from contracts, restore PGA Tour eligibility or settle disciplinary questions. Each path depends on contracts, tour rules and the final restructuring. Yet the filing increases the pressure on everyone involved to obtain clarity before 2027 schedules and memberships are finalized.
The PGA Tour can now observe rather than negotiate from urgency. LIV's future is being determined through a financing and court process, not a merger announcement. The DP World Tour may become even more important as a competitive home for eligible players seeking world-ranking points and a reliable schedule.
The league survived the rumor. Now it must survive the case.
LIV has presented Chapter 11 as a tool for its next era, and that description is legally plausible. Many companies use restructuring to shed unsustainable obligations and continue. The filing is still an admission that the previous capital structure could not carry the business forward.
The next meaningful evidence will come from court documents and signed commitments: approved interim financing, creditor treatment, player participation, exit funding and a credible 2027 schedule. Marketing language cannot substitute for those milestones.
LIV Golf is not dead tonight. It is also no longer operating on faith alone. With more than $500 million in debt and a proposed player-owned future, the league has traded financial freedom for a supervised chance to survive. What emerges—if the plan is approved—will be smaller, more accountable and fundamentally different from the operation that disrupted professional golf in 2022.